The average cost of a student belongings insurance theft claim has doubled in just three years, according to Aviva, as laptops, phones and bikes remain the items most frequently targeted by thieves when students head to university.
Aviva says the average value of a student possessions claim rose from £781 to £1,766 between 2022 and 2025, a near-doubling that underlines just how much more students are carrying with them and how costly it can be when those items go missing or are damaged.
Theft accounts for the majority of student claims
The theft problem is more widespread than many students heading off for freshers’ week may realise. Insurance Today reports that theft accounts for 56% of student insurance claims, well ahead of accidental damage. Items are taken from student accommodation, cars, public transport, and bars and restaurants.
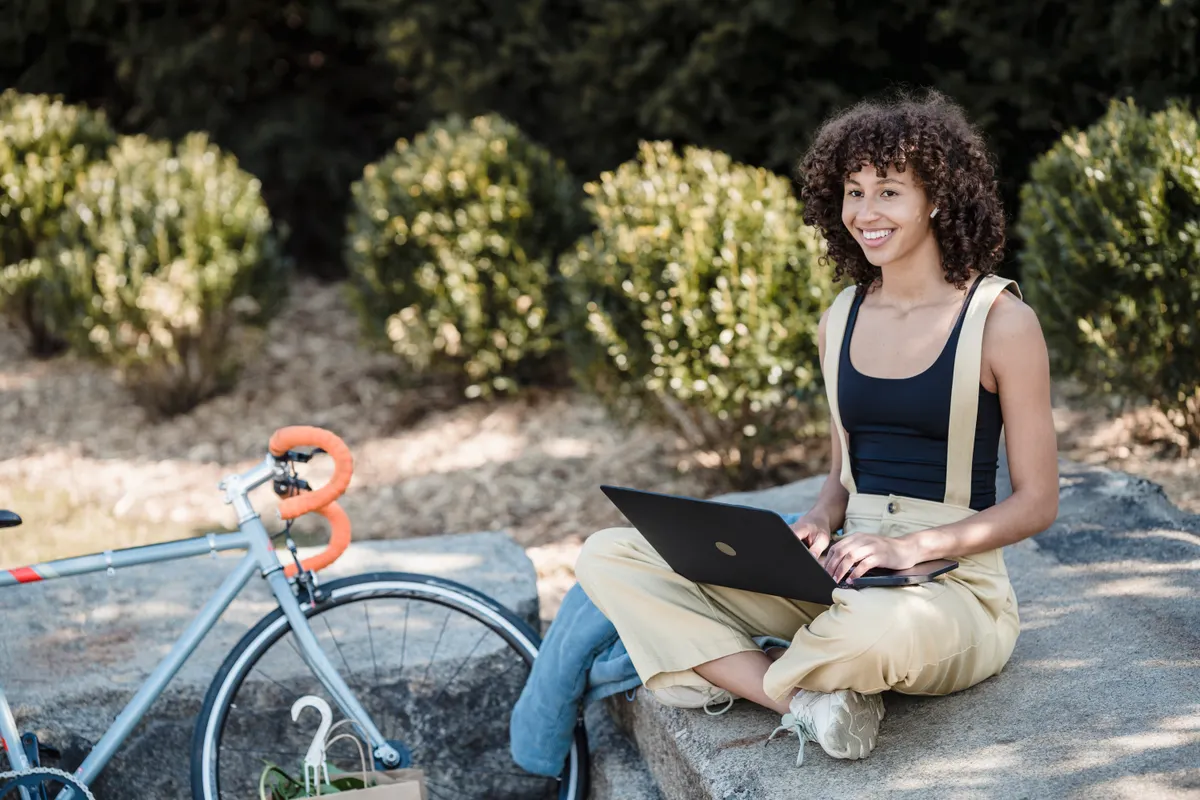
Laptops, computers and mobile phones are among the most common items lost. ‘Laptops, computers and mobile phones play a vital role in student life, but they can also be attractive targets for opportunistic thieves due to their value and portability,’ said Steven Jackson, Aviva’s home product manager.
His practical advice for students includes leaving expensive or sentimental belongings at home where possible, locking up valuables and keeping them out of sight when out and about, and staying aware of when devices are left unattended, for instance, when using a laptop to hold a spot in a library or café.
Bicycles and the student belongings insurance theft picture
Bikes deserve special attention. The Guardian has reported that one in five student possessions claims (19%) relates to bicycles, making them a far larger slice of the problem than many might expect. University towns and cities, with their dense concentrations of cycles and variable lock-up facilities, are fertile ground for bike thieves.
Students bringing a bike to university may need to pay extra on top of a standard contents insurance policy to make sure it is covered, particularly if they also want protection when the bike is taken out rather than left at their accommodation.
How to check whether you are already covered
Before spending money on a new policy, the Association of British Insurers (ABI) recommends checking what cover already exists. Some student halls of residence include basic insurance, and a parent’s home contents policy may extend to a child living away at university. It is worth reading the small print on both before assuming you need to buy something new.
If there is no existing cover, a contents insurance policy can protect belongings against theft, damage or destruction. The ABI advises students to draw up an inventory of everything they are taking, from electronics and clothes to furniture, and to add up the cost of replacing each item. That total determines how much cover is needed, and it is worth checking the maximum single-item limit on any policy as well as the overall sum insured.
‘This type of policy covers the cost of replacing or repairing your possessions if they are damaged, destroyed or stolen, giving you peace of mind that you’re protected should something go wrong,’ the ABI said.
Driving to university brings its own insurance obligations
Students taking a car to university face a specific legal requirement. Car insurance is compulsory under UK law, and insurers must be told if the vehicle is now being kept at a new address. If the car belongs to a parent but the student has become the main driver, the insurer must be notified of that change too. Failing to do so is not just a policy matter, it is illegal.
With the average student claim now standing at £1,766, getting the right cover in place before term starts is considerably cheaper than discovering a gap in it after something goes missing.